TL;DR
CBRE’s latest data shows logistics warehouses in São Paulo are at their highest occupancy rate since 2008. This indicates strong demand for industrial space, driven by e-commerce growth and supply chain shifts. The trend highlights a significant change in the regional logistics market.
Logistics warehouses in São Paulo are currently operating at their highest occupancy levels since 2008, according to a recent report by CBRE. This surge in occupancy underscores a robust demand for industrial space in the region, driven by ongoing shifts in supply chains and e-commerce expansion. The development is notable for its potential impact on regional real estate markets and logistics operations.
CBRE’s latest analysis indicates that the occupancy rate of logistics warehouses in São Paulo has reached approximately 91%, the highest since 2008. The increase is attributed to a combination of factors, including rising e-commerce activity, supply chain restructuring, and an overall shortage of available industrial space in the metropolitan area. The report highlights that new developments are struggling to keep pace with demand, leading to a tightening market.
Industry experts note that this trend reflects a shift in regional logistics strategies, with companies prioritizing proximity to urban centers to meet consumer expectations for faster delivery times. The high occupancy rate is also seen as a sign of confidence in São Paulo’s role as a logistics hub, despite broader economic uncertainties. CBRE’s data suggests that landlords are able to command higher rents, further incentivizing new construction and leasing efforts.
Implications of Record-High Warehouse Occupancy in São Paulo
The high occupancy rate in São Paulo’s logistics warehouses is significant because it indicates a strong, sustained demand for industrial space in one of Latin America’s largest markets. This trend can lead to increased rental prices, stimulate new developments, and influence investment strategies in the region. It also reflects broader shifts in supply chain logistics, notably the acceleration of regional distribution networks driven by e-commerce growth. For businesses, this means greater access to reliable warehousing options but also potential cost increases.
Furthermore, the trend may signal a tightening market that could impact supply chain flexibility and costs for companies operating in or relying on São Paulo’s logistics infrastructure. Policymakers and developers will need to consider how to balance demand with sustainable growth, ensuring that infrastructure keeps pace with the rising occupancy levels.
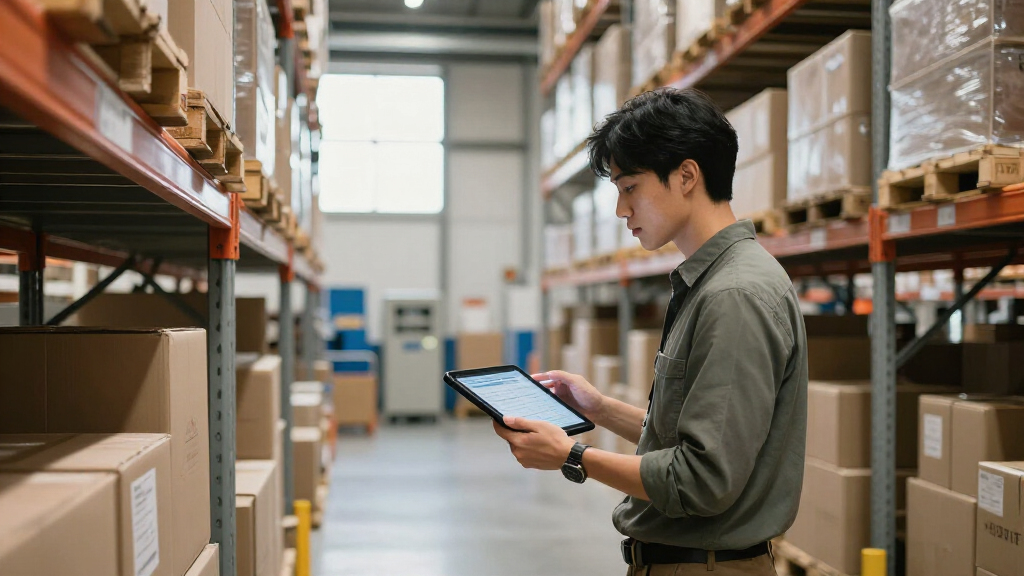
industrial warehouse shelving units
As an affiliate, we earn on qualifying purchases.
As an affiliate, we earn on qualifying purchases.
Historical Trends and Current Market Dynamics in São Paulo Logistics
São Paulo has long been a central hub for logistics and industrial activity in Brazil, with occupancy rates fluctuating over the past decade due to economic cycles, infrastructure investments, and market shifts. The 2008 peak was driven by rapid urbanization and industrial expansion, but subsequent years saw periods of slowdown and oversupply. The recent spike in occupancy, now reaching levels last seen in 2008, reflects a reversal of those trends, largely driven by the e-commerce boom and supply chain reconfigurations following the COVID-19 pandemic.
Prior to this, the market experienced periods of vacancy and stagnation, but recent data from CBRE indicates a tightening of available space, with vacancy rates dropping below 10%. This pattern aligns with similar trends in other major logistics markets globally, where demand outpaces supply amid changing consumer behaviors and business strategies.
As an affiliate, we earn on qualifying purchases.
Unconfirmed Factors Behind the Market Surge
While data confirms the high occupancy levels, the specific drivers behind this surge are still being analyzed. It is not yet clear how much of the demand is driven by new companies entering the market versus existing tenants expanding their space. Additionally, the impact of recent economic policies, infrastructure investments, or global supply chain disruptions remains to be fully assessed. Market analysts caution that some of these factors could change, potentially affecting future occupancy trends.
As an affiliate, we earn on qualifying purchases.
Future Outlook and Market Developments to Watch
Next steps include monitoring whether new warehouse developments can keep pace with rising demand, and if rental prices continue to escalate. Industry stakeholders will also be watching for potential shifts in supply chain strategies, such as diversification of logistics hubs or technological innovations that could influence space requirements. CBRE and local developers are expected to release updated forecasts in the coming quarters, which will clarify whether this high occupancy rate sustains or begins to stabilize.
As an affiliate, we earn on qualifying purchases.
Key Questions
What is driving the high occupancy rate in São Paulo’s logistics warehouses?
The surge is primarily driven by increased e-commerce activity, supply chain restructuring, and a shortage of available industrial space in the region, according to CBRE and industry analysts.
How does this occupancy rate compare to previous years?
The current occupancy rate of approximately 91% is the highest since 2008, surpassing recent years’ levels and indicating a tightening market.
What are the implications for rental prices?
Higher occupancy rates typically lead to increased rental prices, as demand outstrips supply, which can incentivize new developments and leasing efforts.
Are there enough new warehouses being built to meet demand?
Construction has struggled to keep pace with demand, leading to a market with limited available space and potential future supply shortages.
What could change the current market trend?
Factors such as economic downturns, policy changes, or shifts in global supply chains could impact demand and occupancy levels in the future.
Source: local